
Electric company cars: a guide for employers
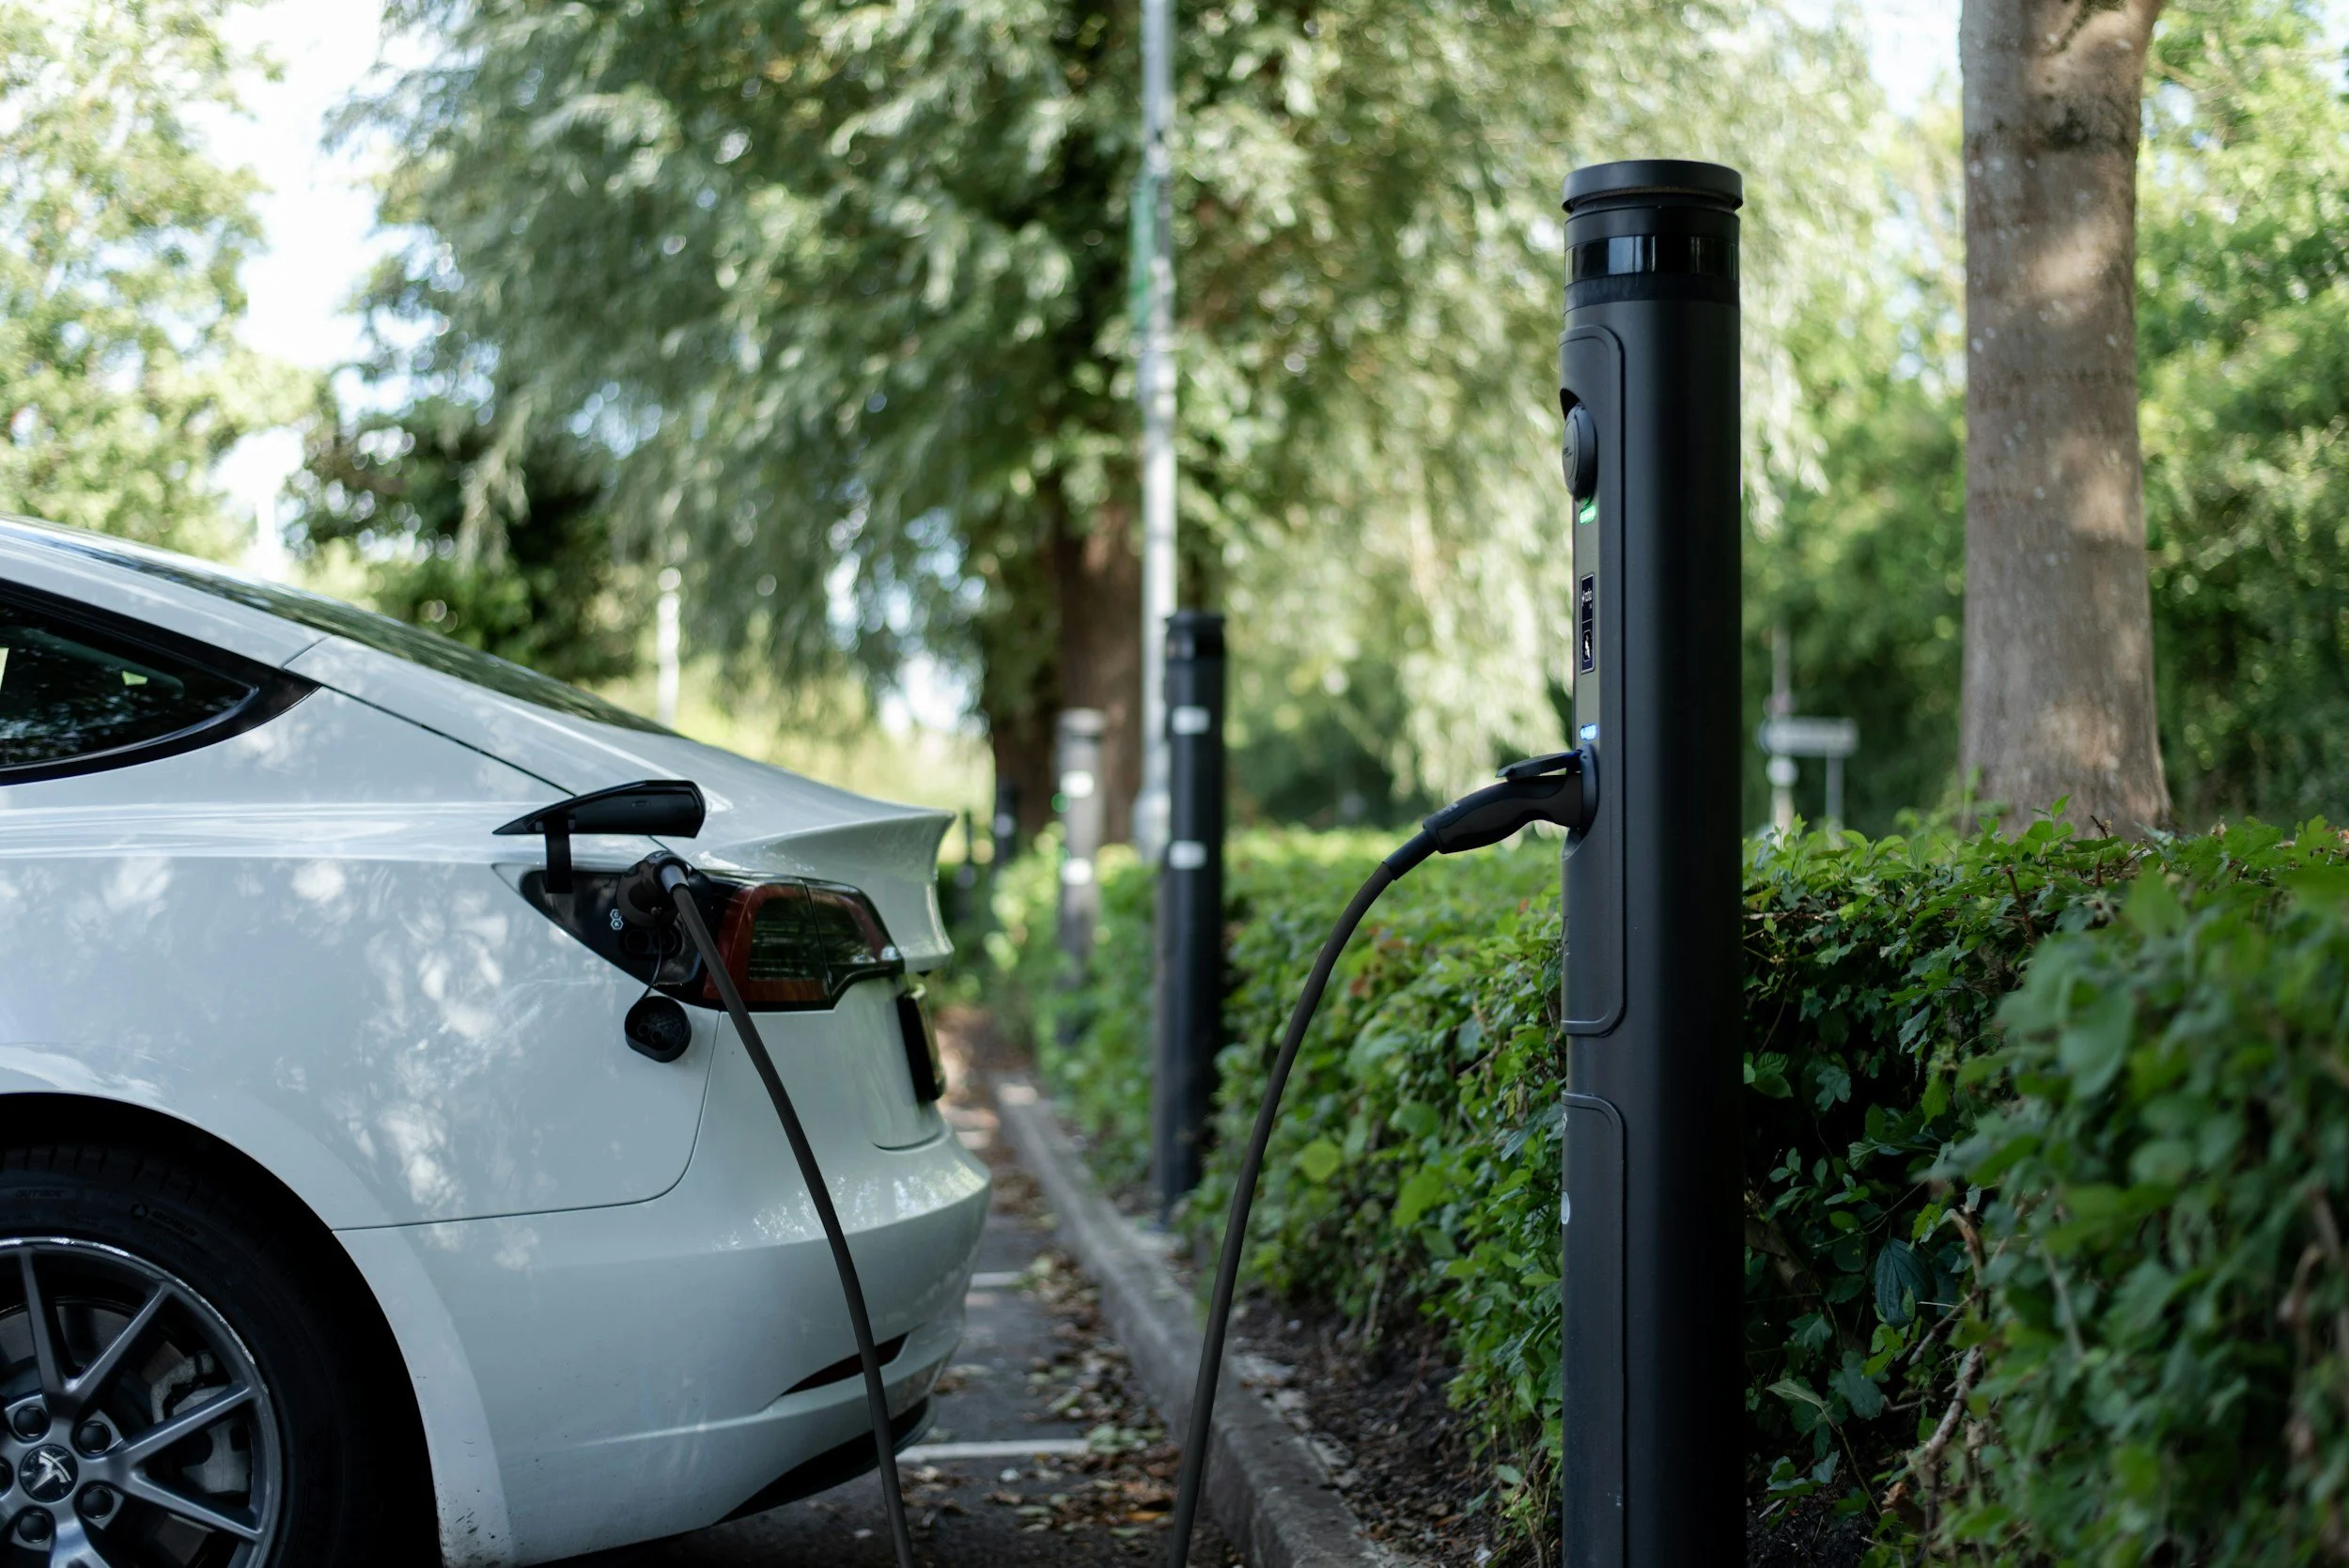
Who this guide is for
This guide is for you if you run a limited company and are thinking about providing an electric car to yourself as a director, or to an employee.
If you are a sole trader or in a partnership, the rules are different and this guide does not apply to you. I cover your position in a separate guide.
All figures are for the current tax year, 6 April 2026 to 5 April 2027, unless stated otherwise.
The short version
Electric company cars are taxed far less than petrol or diesel ones.
The person who drives the car pays a small amount of extra income tax each year, usually collected through their tax code.
The company pays a small amount of extra National Insurance once a year.
If the company buys a brand new electric car before 31 March 2027, it can usually deduct the whole cost from its profits that year, cutting its corporation tax bill.
Charging the car at work, or at home on a company-paid charger, is usually tax free.
The tax on electric company cars goes up every year, so look at the whole period you will have the car, not just year one.
How the driver is taxed
Why is there any tax at all? If your company gives you a car that you can use for personal journeys, including driving to and from work, HMRC treats it as a perk. This is called a benefit in kind. You pay income tax on it as if it were extra salary, even though no money changes hands.
How much? HMRC takes the car's list price and applies a set percentage. For a fully electric car the percentage is 4% this tax year. So on a car with a list price of £45,000, you are treated as receiving £1,800 of extra pay.
If you pay basic rate tax (20%), that costs you £360 a year, about £30 a month. If you pay higher rate tax (40%), it costs £720 a year, about £60 a month.
Which price is used? The list price of the car when new, including VAT, delivery and any extras. This applies even if the company bought it second hand or got a discount. You will see this called the "P11D value", named after the form used to report perks to HMRC. If you pay towards the cost of the car yourself, up to £5,000 of that is taken off.
The percentage goes up each year. The government has already set the rates up to April 2030:
| Tax year | Percentage for electric cars | Yearly tax on a £45,000 car (20% taxpayer) | Yearly tax on a £45,000 car (40% taxpayer) |
|---|---|---|---|
| 2025/26 | 3% | £270 | £540 |
| 2026/27 | 4% | £360 | £720 |
| 2027/28 | 5% | £450 | £900 |
| 2028/29 | 7% | £630 | £1,260 |
| 2029/30 | 9% | £810 | £1,620 |
For comparison, most petrol and diesel cars are taxed at between 25% and 37%.
What about hybrids? Plug-in hybrids are currently taxed at lower rates too, but from April 2028 most will jump to 18%. That makes them much less attractive as a company car.
Electricity for personal journeys. With a petrol company car, there is a large extra tax charge if the company pays for fuel for personal use. That charge does not apply to electricity.
What it costs the company
The company pays employer's National Insurance on the value of the perk. This is called Class 1A National Insurance and the rate is 15%. It is paid once a year, by 22 July after the end of the tax year.
On a £45,000 electric car this year, that is £1,800 x 15% = £270.
Electric and petrol side by side
Here is the same £45,000 car as an electric model and as a typical petrol model, for this tax year:
| Electric | Petrol | |
|---|---|---|
| Tax percentage | 4% | 30% |
| Perk the driver is taxed on | £1,800 | £13,500 |
| Driver's yearly tax (20% taxpayer) | £360 | £2,700 |
| Driver's yearly tax (40% taxpayer) | £720 | £5,400 |
| Company's yearly National Insurance | £270 | £2,025 |
Over four years. If the company keeps the car from April 2026 to April 2030, a 40% taxpayer would pay £4,500 in total and the company £1,687.50. That is still far cheaper than petrol, but the bill in year four is more than double year one.
To check the figures for a particular car, use HMRC's company car tax calculator.
How the company gets tax relief on the car
When a company buys something it will keep, like a car or equipment, it cannot simply deduct the cost from its profits. Instead it claims capital allowances: HMRC's system for deducting the cost of larger items, such as vehicles and equipment, from the company's profits, which reduces its tax bill.
Electric cars get very generous treatment:
| How the company gets the car | How much it can deduct |
|---|---|
| Buys it brand new, before 31 March 2027 | The whole cost, in the year it buys the car |
| Buys it second hand | 14% of the remaining cost each year, spread over many years |
| Leases it | The lease payments, in full, as they are paid |
| Installs a charge point at the business premises, before 31 March 2027 | The whole cost, in the year it is installed |
What that means in pounds. A company buying a new £45,000 electric car can deduct the full £45,000 from its profits, saving between £8,550 (at 19%) and £11,250 (at 25%) in corporation tax that year. Bought second hand, it could deduct only £6,300 in year one.
Will the full deduction end? It is due to end on 31 March 2027, but has been extended several times before. Watch for any announcement in the Budget on 28 October 2026. I will update this guide once it is published. If it does end, new electric cars will get 14% a year instead.
Think about cash flow. Buying a car outright can take a large amount of cash out of the business in one go, while the tax saving only comes through when the corporation tax bill is due. It is worth checking that the company will still have enough cash to cover its day to day running costs, tax bills and any dividends you plan to take. Leasing or finance spreads the cost, but brings its own costs. I can help you look at the figures before you commit.
Timing the purchase around your year end. The full deduction is given in the financial year the car is bought. If your year end is close, buying just before it brings the tax saving forward by a whole year. For example, with a 31 December year end, a car bought on 15 December is deducted that year. Bought on 5 January, the saving comes a year later. The company must be committed to paying before the year end and, on hire purchase, the car must be delivered and in use. The tax saving is a welcome bonus, but it works best when the business was planning to get a car anyway.
Good to know:
Your personal use of the car does not reduce the company's tax relief.
If the company later sells the car, the sale price is usually added back to its profits and taxed.
If you lease, you deduct the lease payments and the leasing company claims the capital allowances.
Charging the car
Most ways of paying for charging an electric company car are tax free, as long as they are set up properly.
| What the company pays for | Extra tax to pay? |
|---|---|
| Charging at or near the workplace | No |
| A charger installed at the driver's home, for the company car | No |
| Solar panels or a home battery installed with that charger | Yes, these are a taxable perk |
| Paying the driver back for home electricity used to charge the company car | No, as long as it only covers the company car |
| A charge card for public charging points | No |
Paying back the cost of business miles. Working out exactly how much electricity went into the car at home can be tricky. To make it simpler, HMRC publishes set rates per mile, updated every three months. From 1 September 2026 they are 7p a mile for home charging and 15p a mile for public charging. The company can pay the driver these rates for business miles without any extra tax.
If the driver uses their own electric car instead. The usual mileage rates apply: the company can pay 55p a mile tax free for the first 10,000 business miles in a tax year, and 25p a mile after that. The 55p rate applies from 6 April 2026, up from 45p.
Road tax
Electric cars will soon pay two separate road taxes, each with a different purpose.
Standard road tax is a flat yearly charge for keeping a car on the road, however much it is driven. Electric cars have paid it since 1 April 2025. A new electric car pays £10 in its first year, then £200 a year. If its list price is over £50,000, there is an extra £440 a year for the next five years.
The pay-per-mile charge is planned to start in April 2028, at 3p a mile for fully electric cars and 1.5p a mile for plug-in hybrids. It replaces the fuel duty that petrol and diesel drivers pay at the pump. The government has set it at around half the fuel duty a typical petrol car pays per mile, so electric cars should stay cheaper to run.
A car driven 10,000 miles a year would pay about £300 a year in pay-per-mile charges, rising with inflation from 2029/30. It is not yet law, but is worth allowing for if you are signing a lease that runs past April 2028. On a leased car, check whether the leasing company will pass the charge on to you.
VAT
A VAT registered company can usually reclaim the VAT on buying a van or other commercial vehicle, but not on a car. The only exception is a car used purely for business and not available for any personal use, such as a taxi, a driving school car or a pool car kept at the business premises overnight. A company car driven by a director or employee will almost never qualify, because driving to and from work counts as personal use.
If you lease the car, the company can usually reclaim half the VAT on the lease payments.
Other things to know
Salary sacrifice. This is where an employee agrees to take a lower salary in return for having the car. Because electric cars are taxed so lightly, both the employee and the company save tax and National Insurance on the salary given up. Check the reduced pay does not fall below the National Minimum Wage, and think about the effect on pension contributions and mortgage applications.
Reporting. At the moment, company car perks are reported to HMRC on a form called a P11D after the tax year ends. From April 2027 they must be reported through the monthly payroll instead. If I run your payroll, I will deal with this for you.
Before you sign
Find out the list price of the exact car, including VAT and any extras
Work out the tax for every year you plan to keep the car, not just the first
Decide whether the company will buy or lease
If buying new, aim to complete before 31 March 2027, and check whether buying before your year end brings the tax saving forward
Agree how charging will be paid for, and put it in writing
Compare with the alternatives, such as using your own car and claiming 55p a mile
There is no single right answer. It depends on how you take your income, how profitable the company is and how many business miles you drive. If you would like me to run the numbers for your company, get in touch with me at Indie Financials.
This guide is general information based on the rules at the date shown. It is not advice for your specific circumstances.